By Uzu Okagbue
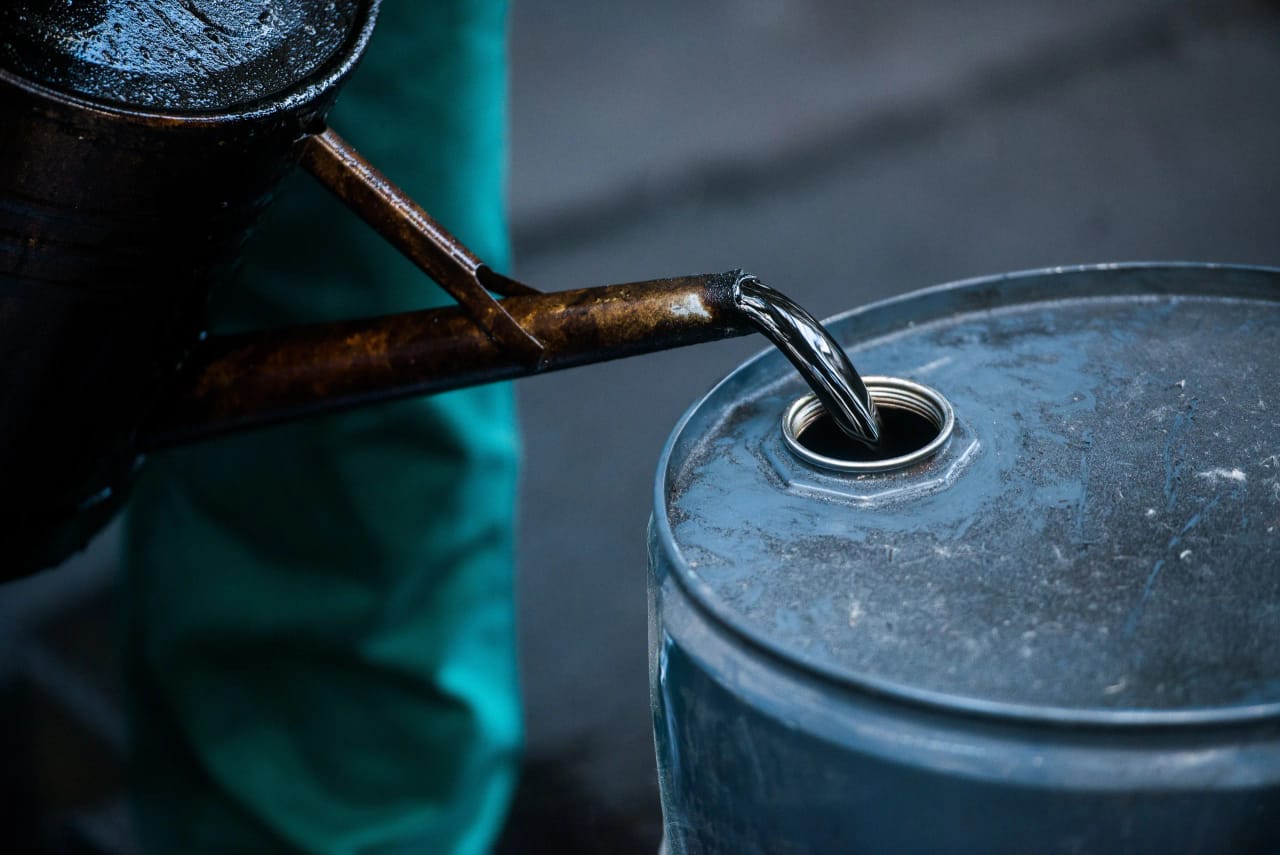
Editor’s Note: Uzu Okagbue throws light on the debate over the recent oil price increase in Nigeria. There has been a global increase in oil prices because of the conflict in the Middle East. In Africa, aside Nigeria, Egypt recently had a 30% increase in oil prices. However, Nigeria’s opposition figures are blaming the government, claiming that the government should have planned to cushion the global oil shock. Okagbue, in this article, faults this narration.
The argument presented that Nigeria would have planned its way out of the global oil shock rests on a shallow reading of the global petroleum economics and betrays a fundamental understanding of how the contemporary oil market functions. What is being offered as economic insight is, in truth, a simplistic narrative that ignores the structural realities of the global energy system and the geopolitical turbulence currently shaping it.
First, the global oil market is not a local supply chain problem that can be insulated by merely warehousing barrels of crude or refined products. Oil is one of the most globally integrated commodities in existence. Prices are determined in a highly interconnected market driven by geopolitical tensions, production quotas, speculative futures trading, shipping risks, and refining constraints. The present volatility is not a Nigerian phenomenon; it is the predictable outcome of escalating tensions in the Middle East, particularly involving Iran, Israel, and the strategic involvement of the United States, within a region that controls the largest share of globally traded crude.
This region sits at the heart of the global supply architecture managed largely by Organization of the Petroleum Exporting Countries. When geopolitical risks threaten production routes, shipping lanes, or production capacity in that corridor, the entire global pricing mechanism responds instantly. Insurance premiums for tankers rise, traders begin hedging aggressively in the futures market, and prices spike even before a single barrel is physically disrupted.
That is precisely what the world is witnessing.
The suggestion that strategic petroleum reserves would meaningfully shield Nigeria from such systemic shocks demonstrates a poor grasp of how those reserves are actually used. Strategic reserves are not instruments for controlling retail prices in the domestic market. They are emergency buffers designed for short-term supply interruptions; natural disasters, refinery shutdowns, or temporary embargoes: not for offsetting prolonged geopolitical conflicts affecting global pricing benchmarks.
Even the largest holders of strategic reserves, such as the United States and China, cannot use them to permanently suppress market prices during major geopolitical disruptions. At best, they release limited volumes to calm markets temporarily. The price signal from global benchmarks still prevails.
Indeed, when the world faced the severe supply disruption following the Russian invasion of Ukraine, multiple advanced economies released tens of millions of barrels from their reserves. Yet global oil prices still surged dramatically. The reserves merely softened the immediate shock; they did not eliminate the price reality dictated by global markets.
This illustrates the fundamental flaw in the argument being advanced.
Nigeria itself, despite being a member of Organization of the Petroleum Exporting Countries and an oil-producing nation, is not insulated from the volatility of the global petroleum system. Oil-producing countries frequently suffer from the very price swings they help generate. When conflict disrupts major supply corridors in the Middle East, the ripple effects extend across OPEC production quotas, shipping logistics, refining margins, and currency markets.
For countries like Nigeria, the consequences can be even more complex. Rising global crude prices increase the cost of imported refined products, intensify foreign exchange pressures, and raise domestic pump prices; especially in a deregulated market where prices reflect international benchmarks.
Thus, the simplistic claim that the problem is merely the absence of a national stockpile ignores the far larger structural forces at play. Petroleum economics is shaped by geopolitical conflict, global supply chains, currency dynamics, refinery capacity, and market speculation. None of these forces disappear simply because a country builds storage tanks.
To reduce a complex global energy shock to the slogan of “failure to plan” is not serious economic analysis. It reflects a misunderstanding of the nature of commodity markets in the twenty-first century. Strategic reserves are tactical tools; they are not magical shields against geopolitical upheaval in the world’s most volatile oil-producing region.
What the current price movements actually reveal is not a lack of planning but the unavoidable reality of participating in a globally integrated energy market where events in the Middle East instantly reverberate across continents, including oil-producing states themselves.
Any analysis that ignores this basic fact is not an economic diagnosis; it is political submission dressed up as policy insight.